 Niall Ferguson: Why Europe Is Burning Young Europeans are taking to the streets in Paris, Madrid, and Brussels. They say they want more investment in schools and housing. They should be protesting a system rigged for their grandparents.
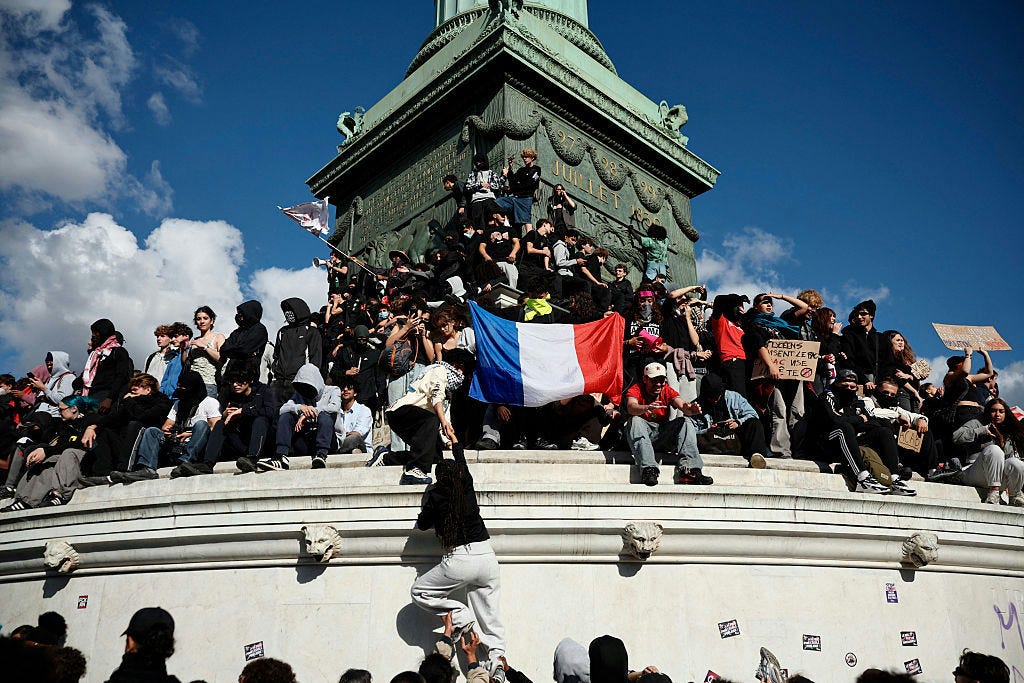
Youth climb the July Column monument during a demonstration demanding better learning conditions in Paris on October 8, 2026. (Simon Wohlfahrt/AFP via Getty Images)
“The most French thing I’ve ever seen” was a couple sipping wine in a sidewalk café, probably discussing Jean-Paul Sartre, while a fire started by protesters raged on the other side of the boulevard. Disappointingly, the video posted on X was from three years ago, but it suited the moment last week. As their national anthem contains the phrase, “Aux armes, citoyens!,” don’t be surprised if, quite regularly, young French people decide to reenact revolutionary scenes. As I write, French schools are burning—set ablaze by high schoolers who say they want more investment in education but for some reason think they can achieve this by filling the streets with garbage, setting it on fire, waving Palestinian flags, and clashing with the police. The latest reincarnations of the sans-culottes are out in force—though, as in 1968, their attire is quite chic. As a cynical friend observed, what the first Communion is for a young Roman Catholic, so the first manifestation is for a young Parisian: a rite of passage. And yet it’s not just France. The kids are out in the streets of Madrid, too, incensed (they claim) about a growing housing crisis. In Brussels the burning issue is government budget cuts. So what’s going on in Europe? No, I don’t think it’s the beginning of Eurozone Crisis 2.0. Those with good memories will recall that the first Eurozone crisis began in 2009 with a Greek debt crisis that spread to other countries. As we shall see, the recent wave of protests has indeed coincided with a French debt crisis that also threatens to spread to other members of the Eurozone. However, if the European Central Bank (ECB) learned anything from the events of 2011–2012 it was that it must stand ready “to do whatever it takes to preserve the euro”—the immortal words of ECB president Mario Draghi in July 2012. If French bond yields go up much higher—say by another 100 basis points (1 percent)—then the ECB has the tools to intervene and stabilize the market...
Become a paid subscriber To support our journalism, and unlock all of our investigative stories and provocative commentary about the world as it actually is, subscribe below. UPGRADE TODAY |