|
Hi everyone,
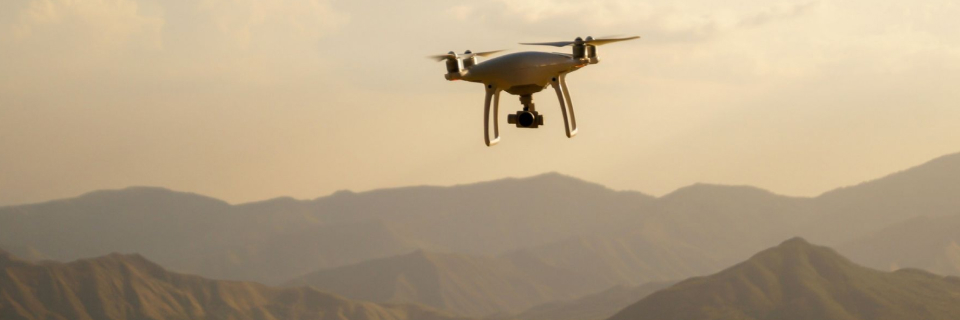
‘Drones’ is one of those themes that’s hard to ignore. Whichever way you look at it, I get the sense that they are ‘the way of the future’ in many regards. The numbers are enormous, the use cases keep multiplying, and the total addressable market (TAM) charts all point up and to the right.
But a big market and a good investment aren’t the same thing, and the gap between them is where most of the money is won or lost.
The parallel I’d draw is AI. Frontier labs are posting revenue growth almost no one has seen before, and yet the question that remains for investors is whether that growth ever turns into durable cash flow and profit. Enormous demand doesn’t help you much if the thing being sold has no moat around it.
Drones strike me as similar. Building a drone, it turns out, isn’t especially hard, lots of companies can do it, which starts to look a lot like commodification. And commodities, however fast the market grows, tend to compete their own margins away.
So the more interesting thought experiment is whether a given drone company has something its rivals don’t… real technical difficulty, network effects, scale, a regulatory edge, anything that lets it earn a return the rest of the field can’t. That’s usually where the counter-drone and specialist niches get more interesting than the hardware itself.
That’s the lesson I took from this week’s Market Insights. To look past the trend and the TAM, and ask what is actually special.
Sincerely,
Mitchell Lawler, Senior Investment Editor
|